Limited Partner Assumptions
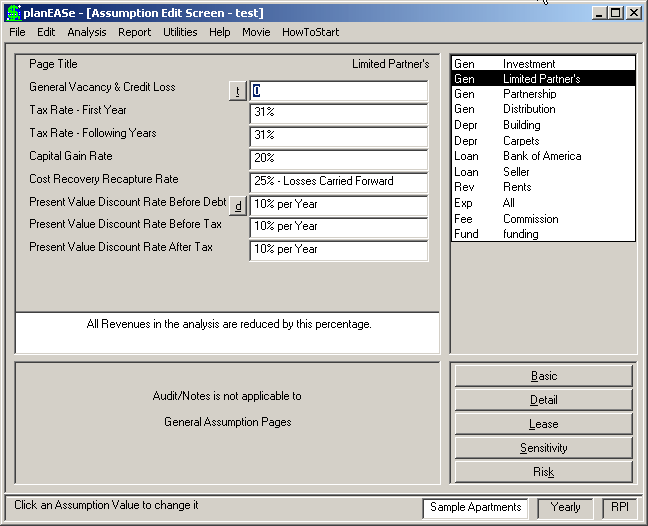
These assumptions are used to calculate the values shown in the Limited Partner / Group Member Projection (Per Unit) and the General Partner / Managing Member Cash Flow Projec- tion pages of the analysis. The experienced planEASe user will recognize these assumptions as being the same as the “Investor’s” assump- tions in the Real Estate Investment Analysis , and planEASe assumes that you wish to use the “Investor’s” assumptions for the “Limited Partner / Group Member” assumptions. You are referred to the Real Estate Investment Analysis for a discussion of the individual assumptions.
As with the Real Estate Investment Analysis , you may choose to pass through any passive losses to the investor by making the Cost Recovery Re- capture Rate negative. In this case, losses will be completely passed through to the investors on the Limited Partner / Group Member Projection (Per Unit) page. Regardless of whether passive losses are passed through to the investors, the losses are always passed through to the General Partner / Managing Member on the General Partner / Managing Member Cash Flow Projection page under the presumption that they are deductible business losses.
If you choose to activate the $25,000 limitation in any year(s) by making the tax rate negative, the limitation applies at the Unit level ($25,000 per Unit). If you are planning an investment for a particular investor where this is required, then, change the Number of Units Issued assumption value to reflect the total investment by the investor if it is not one unit.
As discussed in the Real Estate Investment Analysis section of this manual, the tax section of the analysis is meant to be merely representative of the results of the investment. Limited Partners / Group Members typically have individual tax considerations, and should be advised to consult their tax advisors as to the tax consequences of their investment in light of their own particular tax situation.