Partnership / Group Assumptions
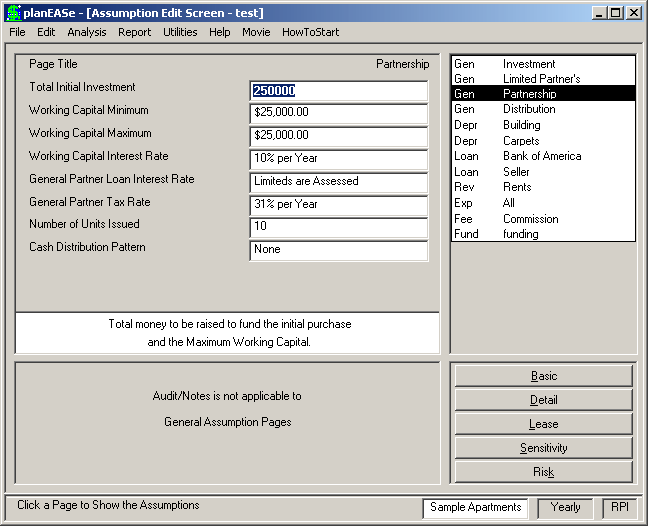
These assumptions deal with the funding of the Partnership. The individual assumptions are:
TOTAL INITIAL INVESTMENT is the amount of money required to be raised to fund the initial purchase of the property and Working Capital Maximum. If the amount entered is less than the sum of the Cash Flow Before Tax at the Buy time and the Working Capital Maximum, planEASe automatically makes up the difference with either an assessment for the remaining amount or a loan from the General Partner / Managing Member, depending on which method has been chosen for funding shortfalls (see below). In the case of the Sample Apartments, the user has chosen to raise $250,000, which is $10,000 less than is necessary for this partner- ship and property.
WORKING CAPITAL MINIMUM is the minimum level of working capital for operations. If less than this amount is available, the Limited Partners / Group Members are assessed or a loan is made by the General Partner / Managing Member to bring working capital to the Working Capital Maximum, depending on the shortfall funding method chosen (see below).
WORKING CAPITAL MAXIMUM is the maximum working capital to be retained in the Partnership / LLC. If more than this amount of cash is available (and cash distribution has begun), the excess is distributed. In our example, $25,000 is the working capital maximum chosen which, when added to the $235,000 Cash Flow Before Tax, means that $260,000 must be raised to initially fund the Partnership.
WORKING CAPITAL INTEREST RATE is the percentage interest rate earned on the Working Capital.
GENERAL PARTNER / MANAGING MEMBER LOAN INTEREST RATE is the percentage interest rate paid on any loans made by the General Partner / Managing Member to fund shortfalls. Any negative value causes the model to fund shortfalls by assessing the Limited Partners / Group Members. In this case, the amount of the negative value is irrelevant to the calculation (that is, -10.00 is functionally the same as -5.00). For the Sample Apartments, the user has chosen a value of -15.00. This means that the Limited Partners are “assessed” for the $10,000 shortfall in the initial funding, and the total initial investment is increased from the $250,000 specified to the $260,000 required.
GENERAL PARTNER / MANAGING MEMBER TAX RATE is the percentage tax rate used to calculate the taxes paid by the General Partner / Managing Member in the General Partner / Managing Member Cash Flow Projection.
NUMBER OF UNITS ISSUED is used to produce the Limited Partner / Group Member Projection (Per Unit) output page. All cash and tax liabilities distributed to the Limited Partners / Group Members are divided by this number to produce the unit forecast. The Sample Apartments General Partner plans to issue 10 units, so the unit price is $26,000.
CASH DISTRIBUTION PATTERN is entered as x.y where y specifies the frequency of cash distribution. A y value of 0 specifies monthly cash distributions, 1 means annual, 2 means semi-annual, and 4 means quarterly. x specifies the first month of the calendar year in which a distribution occurs under the specified pattern, where the months are numbered 1 through 12. Thus a value of 12.1 specifies annual cash distributions each December, and 1.4 means quarterly distributions each January, April, July, and October.