Distribution Assumptions
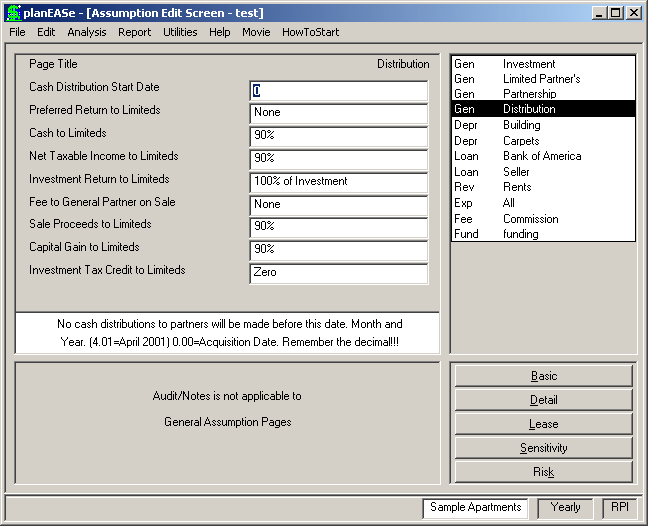
These assumptions deal with the Partnership / LLC methods and formulas for distributing cash and tax liabilities between the Partners / Mem- bers. For both on-going operations and upon sale of the property, Partnership / LLC cash is distributed according to a “Stepdown Alloca- tion”. “Stepdown” means that, step-by-step, cash is allocated according to the following rules, until no more cash remains to be allocated. When all cash available has been allocated, any remaining allocations (if any) are not performed. The cash available for allocation is the total cash available (at sale), or the total cash available less the maximum working capital (for on-going operations). The Stepdown Allocation is:
Stepdown Allocation of Funds Available for Distribution
FIRST: To pay any interest due to the General Partner / Managing Member on any loans he has made to the Partnership / LLC pursuant to funding shortfalls
SECOND: To repay the principal amounts of any loans from the General Partner / Managing Member
THIRD: To pay any arrearage for the Preferred Return to the Limited Partners / Group Members
FOURTH: To pay the Preferred Return for the period to the Limited Partners / Group Members
FIFTH: If the property has been sold, to repay the specified percent of the total investment by the Limited Partners / Group Members
SIXTH: If the property has been sold, to pay the specified fee to the General Partner / Managing Member on sale
SEVENTH: Any remaining cash is split between the Partners / Members according to the percentage specified (which percentage may be different for on-going operations and final distribution on sale).
Because every sale in a Unit Sales project represents a sale of Partnership / LLC Assets, the Stepdown Allocation of Funds for Unit Sales analyses is different from this table. Unit Sales Partnerships / LLCs follow the distribution rules in the Stepdown Table on page 189.
The assumptions specifying the numbers in these cash distributions and the allocation of tax liabilities are:
CASH DISTRIBUTION START DATE is the date on which the Partnership / LLC will begin distributing cash. Until this time, the Partnership / LLC retains all cash and earns interest on it. After this date, the system distributes all cash in excess of the Minimum Working Capital according to the Stepdown Allocation. A zero value defaults to the Acquisition Date. This date may be used to fund a reserve for later negative cash flows
(such as deferred maintenance, for instance). In such cases, put the reserve into the Initial Investment amount so that the initial investment is sufficient to cover the initial cash needs, the maximum working capital and the reserve required. Then set this date beyond the date of the negative cash flow, and planEASe will retain the money until it is required.
PREFERRED RETURN TO LIMITEDS / MEMBERS is the percent preferred return discussed in steps three and four of the Stepdown Allocation. The preferred return is computed based on the total investment made by the Limited Partners / Group Members at the time the return is paid. Thus, if a staged investment is planned, the amount of the preferred return to be paid annually grows as the additional investments are made. If the percentage is positive the preferred return is cumulative (that is, if cash is not available to pay the return in one year the amount of the arrearage is added to the preferred return due for payment when such cash is available). Any arrearage does not compound. If the percentage is negative the preferred return is not cumulative, and no arrearage is computed.
CASH TO LIMITEDS / MEMBERS is the percentage referred to in step seven of the Stepdown Allocation. A value of 90 means that, after all previous cash allocations have been performed, 90% of the remaining cash from operations is distributed to the Limited Partners / Group Members, and the remaining 10% goes to the General Partner / Managing Member.
NET TAXABLE INCOME TO LIMITEDS / MEMBERS is the percentage of the Taxable Income computed in the Partnership /Group Taxable Income Projection output page that is allocated to the Limited Partners / Group Members. For the Sample Apartments, 90% of these amounts is allocated to the Limited Partners, and the remainder is allocated to the General Partner.
INVESTMENT RETURN TO LIMITEDS / MEMBERS is the percentage of the total investment made by the Limited Partners / Group Members which is to be returned to the them pursuant to step five of the Stepdown Allocation. In most cases where such an allocation step is specified, the percent is 100% as shown here. If the assumption value here is -1.00 (minus 1) then planEASe returns an amount to the Limited Partners / Group Members in this allocation step such that the total of that amount plus all previous cash distributed to them during operations is equal to their total investment.
FEE TO GENERAL PARTNER / MANAGING MEMBER ON SALE is the fee to be paid to the General Partner / Managing Member (if any) upon the sale of the property pursuant to step six of the Stepdown Allocation. If an amount greater than 100 is entered, the model presumes that it is a dollar amount. If the amount is 100 or less, the model assumes that it represents a percentage of the total cumulative preferred return paid to the Limited Partners / Group Members during the course of the operation of the Partnership / LLC. (Use of this feature requires that the preferred return be planned as cumulative. The feature does not work with non cumulative Preferred Returns.) A value of zero eliminates any such fee from the calculation. This fee is normally assumed to represent an allocation of Partnership / LLC cash among the Partners / Members, and therefore does not give rise to tax deductions or taxable income. If you want to have the fee deducted by the Partnership / LLC and added to the General Partner / Managing Member Fees, enter the amount or percentage as negative. In this case, the fee is still shown in the “Distributed to General” column, but is also added to the “Taxable Income” for the General Partner / Managing Member Cash Flow Projection and subtracted from the “Ordinary Income” column of the Limited Partner / Group Member Projection (Per Unit) .
SALE PROCEEDS TO LIMITEDS / MEMBERS is the percentage of Partnership / LLC cash allocated to the Limited Partners /Group Members pursuant to step seven of the Stepdown Allocation upon sale of the property and final distribution of the Partnership /LLC assets. In the case of the Sample Apartments, 90% of that cash is allocated to the Limited Partners, with the remaining 10% going to the General Partner.
CAPITAL GAIN TO LIMITEDS / MEMBERS is the percentage of the tax liability for the Partnership / LLC capital gain on sale of the property which is allocated to the Limited Partners / Group Members. In the example, 90% of the capital gain goes to the Limited Partners, and 10% goes to the General Partner.
INVESTMENT CREDIT TO LIMITEDS / MEMBERS If the Partnership / LLC generates Investment Tax Credits, this assumption enables you to allocate the Credits between the Partners / Members. Such allocated credits are shown in the Limited Partner / Group Member Projection (Per Unit) and the General Partner / Managing Member Cash Flow Projection as additions to the “Taxes” columns on those pages.