Source and Use of Proceeds
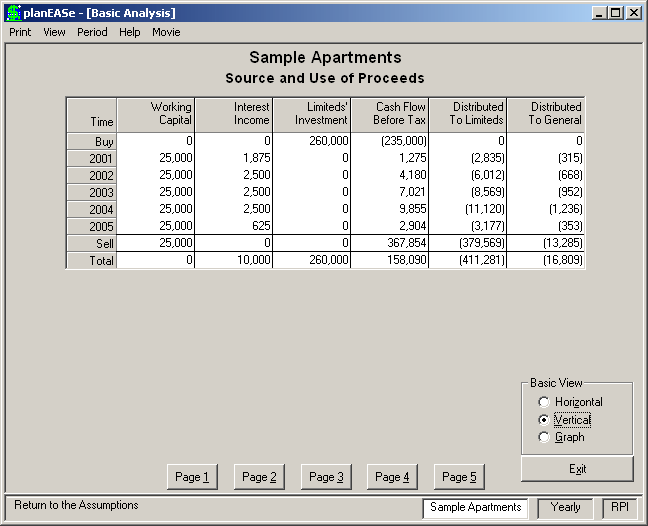
This page details the projected accounting of funds within the Partnership / LLC, showing all the funds received, as well as the projected disbursements to the Partners / Members.
Working Capital shows the working capital balance at the begin- ning of the period. The value is zero at inception since no money has been raised at that time. The working capital remains at the maximum level specified throughout the operation of the Part- nership / LLC, since any amounts greater than that maximum are automatically disbursed. If the Cash Flow Before Tax contained negative values, those negative cash flows would be financed from working capital, and the working capital balance would decrease until the mini- mum working capital amount was reached. Beyond that point, any shortfalls are automatically funded to increase working capital to the maximum amount specified by additional investments or General Partner / Managing Member loans, as chosen by the user. The exception to this rule is when the user delays disbursements through use of the Cash Distribution Start Date assumption. In this case, the working capital grows and shrinks with operations until disbursements are allowed by this assumption. All working capital is disbursed at the sale of the property in the final distribution of funds.
Interest Income shows the interest earned on the working capital, controlled by the percentage specified as the Working Capital Interest Rate.
Limiteds’ Investment shows the capital invested by the Limited Partners / Group Members. Any assessments to raise needed funds are shown here, as well as any additional investments specified in Funding Pages. Thus the $260,000 shown here represents the $250,000 investment specified, plus an assessment of $10,000 to raise the necessary $235,000 down payment plus $25,000 working capital.
Cash Flow Before Tax is the same as the last column of the Before Tax Cash Flow Projection , representing the money flowing in and out of the Partnership / LLC from the operation of the property.
Distributed to Limiteds and Distributed to General The sum of the first four columns in any year represents the amount of cash available for distribution to the Partners / Members. Since the amount of the Maximum Working Capital is reserved from distribution, this amount is subtracted from the cash available, and the remainder is distributed to the Partners / Members in Distributed to Limiteds / Members and Distributed to General / Manager according to the Stepdown Allocation described in the Distribution Assumptions section. In the example, $1,875 plus $1,275, or $3,150 is available for distribution in 2001, and that amount is allocated 90% ($2,835) to the Limited Partners, and 10% ($315) to the General Partner, according to the assumptions.
The amounts shown in these categories are generally negative because they represent cash outflows from the Partnership / LLC to the Partners / Members. If you have chosen to fund shortfalls with loans from the General Partner / Managing Member, the amount of these loans (if any) are shown as positive amounts in Distributed to General / Manager category, and any interest on the loans shows as negative amounts in that category. The total cash received by the Partnership / LLC is always equal to the total disbursed over the life of the Partnership / LLC, as expressed by the column totals on this page.
This page is best read (and understood) horizontally. Reading in that fashion, starting with the first line, the Partnership raises $260,000 to pay $235,000 for the down payment on the property and partnership expenses, leaving $25,000 working capital to begin operations in 2001. During 2001, $1,875 is earned in interest on the working capital, and $1,275 is received in cash flow from the property. This total of $3,150 is distributed $2,835 to the Limited Partners, and $315 to the General Partner, leaving $25,000 working capital to begin 2002.