Limited Partner / Group Member Projection (per Unit)
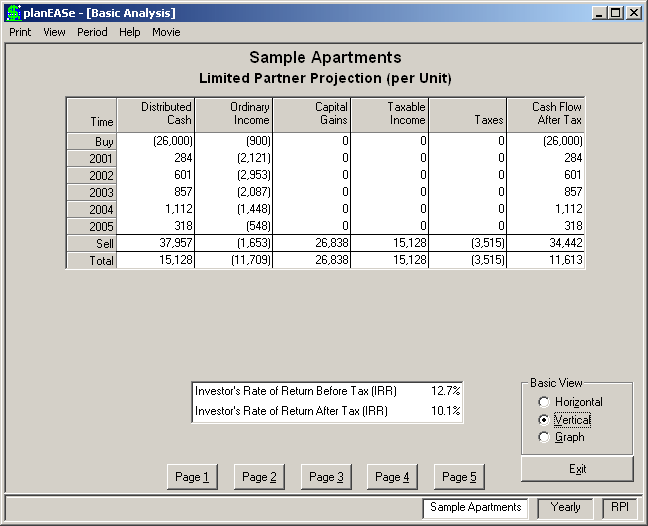
This page projects the results of an investment in one unit of the Partnership by a Limited Partner / Group Member, both before and after tax.
Distributed Cash represents the sum of the “Limiteds’ / Members’ Investment” and “Distributed to Limiteds / Members” columns of the Source and Use of Proceeds , divided by the Number of Units Issued assumption value. Since 10 units are planned to be issued, the corresponding unit investment is $26,000 ($260,000 divided by 10), which is shown in the first column (“Distributed Cash”). The remaining values in this column represent one-tenth of the cash distributed to the Limited Partners in the Source and Use of Pro- ceeds page. The Internal Rate of Return of this column is shown below as the Investor’s Rate of Return Before Tax (12.7%). This IRR is lower than the 14.2% Rate of Return Before Tax because of the deduction of the General Partner distributions from cash available during operations and at sale, as well as the additional investment required for working capital in the partnership mode.
Ordinary Income shows the amount of the “Ordinary Income” in the Partnership / Group Taxable Income Projection allocated to the unit investor. For instance, in 2003 the Partnership Ordinary Income is projected to be -$23,188. Ten percent of this is allocated to the General Partner, leaving -$20,870 for the Limited Partners. Dividing by the ten units issued, -$2,087 is allocated to each unit, as shown here.
Capital Gain shows a similar allocation of the gain on sale. The total amount of the gain is the net sale price ($1,174,104 from the Before Tax Cash Flow Projection ) less the original basis ($1,025,000 from the Before Tax Cash Flow Projection ) plus the depreciation taken ($149,091 from the Partnership Taxable Income Projection ), or $298,195. According to the Limited Partner Share of Capital Gain assumption, 90% of this amount ($268,375) is allocated to the Limited Partners, and each unit’s share is $26,838.
Taxable Income is the sum of the allowable “Ordinary Income” column and the “Capital Gain” column, showing the total amount of taxable income for the unit investment. In this case, the losses shown in ordinary income are not allowable due to the Passive Loss Limitation, and those losses are carried forward to the time of sale. Note that the total taxable income for the investment ($15,128) is the same as the total Distributed Cash received by the investor.
Taxes shows the amount of tax paid by the investor based on the Taxable Income and the tax rate assumed for each year in the Limited Partner / Group Member Assumptions.
Cash Flow After Tax
is the sum of the “Distributed Cash” and the “Taxes” columns, showing the total cash benefit of unit ownership including the taxes. The Internal Rate of Return for this column of cash flows is shown below as the Investor’s Rate of Return After Tax (10.1%).