Unit Sales Draw Page
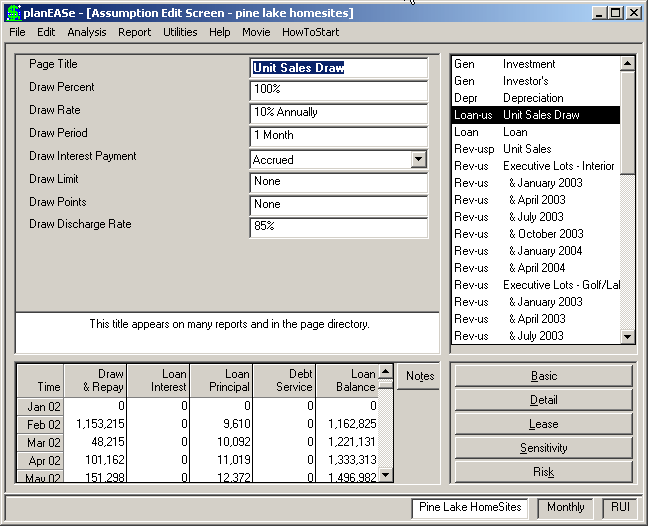
A Unit Sales Draw Page is a Loan Page Sub- Type generated by entering a Unit Sales Dialog, accessed by choosing Edit/Unit Sales... if you have the optional Monthly Extension . This Page will only be generated if you have checked Generate Draws in that Dialog. You cannot enter a Unit Sales Draw Page in any other way. You can, however, edit any of the assumption values shown, once the Page has been generated by the Unit Sales Dialog, and the Unit Sales Draws generated in the resulting analysis will correspond to the edited values. Additionally, appropriate assumption values of the Unit Sales Draw may also be varied in Sensitivity and Risk analyses. You may discern a Unit Sales Draw Page in the Assumption Page List by its Page Abbreviation: Loan-us. The assumptions in a Unit Sales Draw Page are:
DRAW PERCENT is the percentage of the eligible costs (the Unit Sales Cost Item entered in the Unit Sales Cost Item Grid times the Draw percentage entered there) included in the Unit Sales Draw Loan. For instance, an entry of 80% here would generate a draw of $72,000 for an item costing $100,000 when the item Draw entry is 90%. The entry is limited to 0-100%.
DRAW RATE is the Annual Interest Rate charged for the Unit Sales Draw Loan.
DRAW PERIOD is the number of months of Unit Sales Spending that will be funded by this Unit Sales Draw. For example, if you enter 3 months here, and $100,000 of spending is scheduled for the current month, $90,000 for the next month, and $80,000 for the following month, the draw for this month will be $270,000, and no further draw will be scheduled until the 4th month following. This allows you to spread the draws, but will increase the interest cost of the loan, since money is drawn earlier than strictly necessary. No provision is made for earning interest on idle drawn money. Unless your loan source limits the number or frequency of draws, limiting this assumption to one month will benefit your project's rate of return. The entry is limited to 1-12 months
DRAW TREATMENT specifies how interest is paid on the draw loan. Interest may be either accrued (paid as the Unit Sales Draw Loan is repaid), or paid (paid currently as incurred).
DRAW LIMIT is the maximum amount allowed to be outstanding for the Unit Sales Draw loan. This includes any accrued interest. A zero value eliminates any consideration of a limit. Once the limit has been reached (including accrued interest), further draws are not allowed until the balance outstanding falls below the limit due to payments generated by Unit Sales according to the Draw Discharge Rate.
DRAW POINTS is the fee sometimes charged by the originator for handling the loan. Values greater than 100 are assumed to be a dollar amount, while values of 100 or less are treated as a percentage of the Draw Limit. Thus an assumption value of 1.5 means that the borrower is to pay 1.5% of the Draw Limit to the
originator. Draw points are charged at the inception of the loan, and are treated like loan interest, as specified in the Draw Treatment assumption.
DRAW DISCHARGE RATE is either:
! if less than or equal to 100, the percentage of NET sales used to pay off the Unit Sales Draw Loan. Every time a Unit Sale occurs, planEASe computes the amount of the sale, subtracts the Sale Cost/Unit to get the Net Sale amount, computes this percentage of the Net Sale, and pays the resulting amount to reduce the Unit Sales Draw loan balance outstanding. If any balance remains outstanding at the end of the holding period, planEASe pays it off, showing the corresponding negative cash flow at the end of the Holding Period.
! if greater than 100, the percentage of the Standard Cost of the Units sold used to pay off the Unit Sales Draw Loan. Every time a Unit Sale occurs, planEASe computes the Standard Cost of the unit(s) sold, multiplies that amount by this percentage, and pays the resulting amount to reduce the Unit Sales Draw loan balance outstanding. If any balance remains outstanding at the end of the holding period, planEASe pays it off, showing the corresponding negative cash flow at the end of the Holding Period.
Sensitivity and Risk Analysis may be conducted with Loan Amount as the chosen Measure. If a Unit Sales Draw Loan has been specified, the Analysis will show the maximum loan balance during the life of the draw loan as the Loan Amount.